
What is a tranche in finance? A tranche is a distinct portion or class of a larger financial deal, usually created so different investors can take different levels of risk and receive different payment priorities. The word appears frequently in securitization, mortgage-backed securities, asset-backed securities, collateralized loan obligations, and structured finance. In simpler financing arrangements, it can also describe a portion of funding released at a particular stage. Understanding the word is easy; understanding why professionals create tranches is more interesting. The key is to see how cash flows, losses, seniority, and returns are divided.
Think of a financial transaction as a building with several floors. Everyone may ultimately depend on the same underlying source of money, but the occupants do not have identical rights. One group may have the first claim on available cash, another may be paid afterward, and a third may receive whatever remains after the higher-priority claims are satisfied. That hierarchy is the heart of tranching. In a securitization, regulators define a tranche in terms of exposures sharing the same seniority level, while the Federal Reserve describes how underlying cash flows can be allocated to different tranches through a predetermined waterfall.
This guide explains what a tranche means, why financial institutions create them, how senior and junior tranches differ, and how losses move through the structure. You will also see how tranches work in MBS, ABS, CLOs, and other financing arrangements. Most importantly, you will learn why a tranche should never be judged simply by its yield or credit rating. The real analysis starts with three questions: What backs it? Where does it sit in the payment hierarchy? And what happens if the underlying assets perform worse than expected?
What Is a Tranche in Finance?
In finance, a tranche is a separate portion or class of a larger financial transaction, with its own contractual rights and characteristics.
The defining feature is that different tranches can have different:
- Payment priorities
- Credit-risk exposure
- Interest rates or coupons
- Maturities
- Expected cash-flow patterns
- Loss-absorption positions
- Credit ratings
- Investor profiles
The term is especially important in structured finance, where a pool of loans or other financial assets may generate cash flows that are divided among several classes of securities.
The Federal Reserve’s regulatory definition describes a tranche as securitization exposures having the same seniority level. In a securitization, the performance of those exposures depends on the underlying pool of financial assets.
Tranche Meaning at a Glance
| Feature | What it means |
| Basic meaning | A portion or class of a larger financial structure |
| Main purpose | Allocate risk, cash flows, and payment priority |
| Common setting | Securitization and structured finance |
| Typical levels | Senior, mezzanine, junior/subordinated or equity |
| Senior tranche | Higher payment priority and generally greater credit protection |
| Junior tranche | Lower payment priority and generally greater loss exposure |
| Return relationship | Higher risk often comes with higher potential yield |
| Key analytical question | What happens to this tranche if the underlying assets underperform? |
The word does not automatically mean “bond,” “loan,” or “investment.” It describes how a larger financial arrangement has been divided.
Why Do Financial Institutions Create Tranches?
At first glance, dividing one pool of assets into several pieces may seem unnecessarily complicated. The reason is that investors do not all want the same exposure.
Suppose a pool of loans generates relatively predictable payments. One investor might prioritize capital protection and payment priority and accept a relatively modest return. Another might be willing to tolerate more credit risk in exchange for a higher potential return.
A single undivided security cannot easily satisfy both preferences. Tranching allows the transaction to create different claims on the same underlying cash flows.
This can provide several advantages:
- Risk allocation: different investors absorb different levels of risk.
- Investor choice: investors can select a position that fits their objectives.
- Financing flexibility: issuers can structure multiple classes with different terms.
- Credit enhancement: subordinated positions can provide protection to senior positions.
- Marketability: dividing cash flows into classes can make a structured product suitable for a broader range of investors.
But there is a trade-off. More customization usually means more complexity. An investor may understand the underlying loans reasonably well and still misunderstand the security if they overlook the waterfall, triggers, or loss-allocation rules.
Expert takeaway: A tranche changes the distribution of risk and cash flows; it does not make the underlying risk disappear.
How Tranches Work: The Basic Structure
The easiest way to understand tranches is to separate two concepts: who gets paid first and who absorbs losses first.
These are closely related in many senior-subordinated structures.
Imagine three classes:
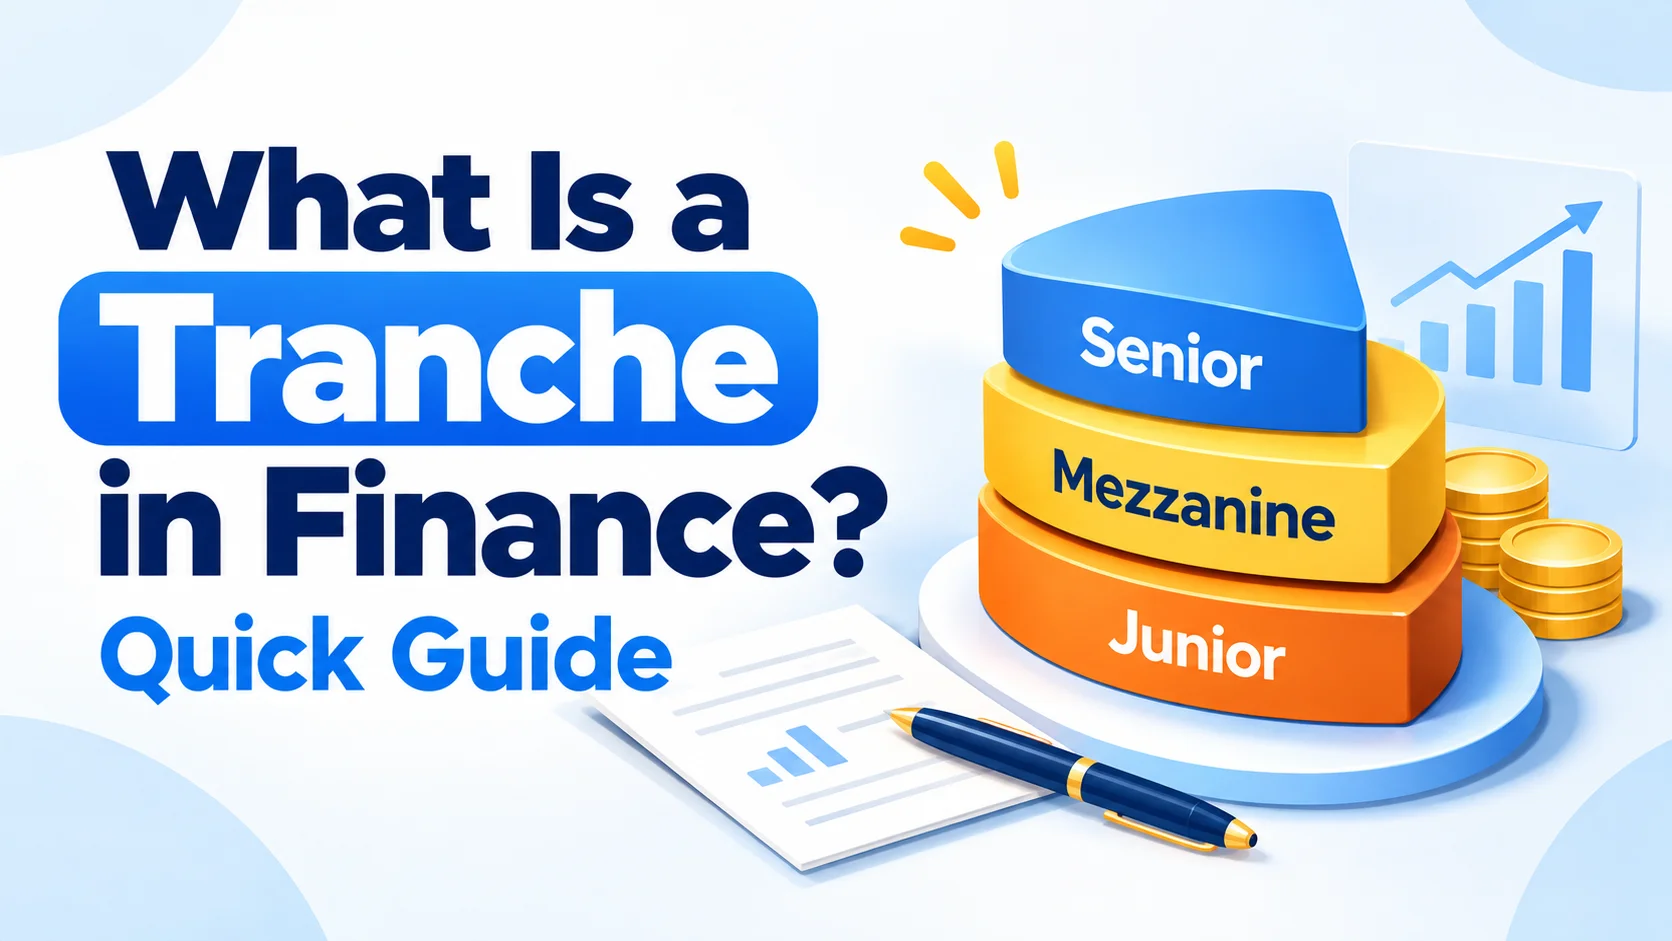
- Senior tranche
- Mezzanine tranche
- Junior or equity tranche
The senior class generally has the highest payment priority. The mezzanine class sits below it, while the junior or equity position generally has the lowest priority.
The exact rules depend on the transaction documents. Some structures contain several senior classes with different payment timing, and a tranche’s label alone may not tell you everything about its risk.
Senior, Mezzanine, and Junior Tranches
| Tranche | Typical position | Relative credit protection | Potential return | Loss exposure |
| Senior | Highest priority | Greatest | Lower | Usually last |
| Mezzanine | Middle | Moderate | Moderate to higher | After junior/equity |
| Junior/equity | Lowest priority | Least | Potentially highest | Usually first |
Senior does not mean risk-free. It means the holder generally has a higher contractual priority than more subordinate positions.
A mezzanine tranche occupies an intermediate position. It may benefit from protection provided by junior capital beneath it, but it is exposed to losses that exceed that protection.
A junior or equity tranche commonly stands at the bottom of the structure. It may absorb losses before other classes and therefore can have a substantially different risk profile.
The Relationship Between Risk and Return
Tranching creates a deliberate trade-off.
If an investor receives payment ahead of other investors and has layers of subordinated capital beneath them, that investor generally has greater protection against credit losses. Because that protection has economic value, the senior investor may accept a lower expected return.
The investor lower in the structure faces more uncertainty. In exchange, that position may offer a higher potential return.
This does not mean the highest-yielding tranche is automatically the most attractive. A higher coupon can simply be compensation for taking substantially more risk.
For example, imagine two securities backed by the same loan pool:
- Security A receives payments first and has substantial junior protection.
- Security B receives payments only after Security A and absorbs losses earlier.
Security B might offer a higher yield. But that extra yield exists for a reason.
The correct comparison is therefore not:
“Which tranche pays more?”
It is:
“How much additional risk am I accepting for that additional return?”
What Is a Tranche Waterfall?
A cash-flow waterfall is the contractual sequence that determines how money generated by the underlying assets is distributed.
Suppose borrowers make $10 million of payments into a securitization structure. The transaction documents specify where that money goes.
A simplified waterfall might look like this:
- Required expenses and fees are paid.
- Senior interest is paid.
- Senior principal is distributed according to the deal rules.
- Mezzanine obligations are paid.
- Junior or equity investors receive remaining amounts.
Actual waterfalls can be far more complicated. They may contain separate rules for interest, principal, reserves, losses, triggers, and different classes.
The Federal Reserve describes securitization cash flows as being allocated among tranches according to a predefined prioritization rule or waterfall.
What Happens When Cash Is Short?
This is where the structure becomes particularly important.
If the underlying assets produce less money than expected, the waterfall determines which investors feel the shortfall first.
In a typical senior-subordinated structure, lower-ranking positions provide credit support to higher-ranking positions. SEC-filed transaction documents commonly describe this arrangement as subordination: a class with lower payment priority can provide protection to classes above it.
That creates an important distinction:
Cash-flow priority and loss priority are related, but they are not necessarily identical in every transaction.
An investor must therefore read the actual deal structure rather than assume that every tranche operates according to the simplest three-level model.
A Simple $100 Million Tranche Example
Consider a hypothetical pool of loans worth $100 million.
The issuer creates three classes:
| Class | Amount | Position | Illustrative role |
| Senior | $70 million | First priority | Receives strongest structural protection |
| Mezzanine | $20 million | Middle | Takes losses after junior protection is exhausted |
| Junior/equity | $10 million | First-loss position | Absorbs initial losses |
These numbers are purely illustrative.
If the underlying loans perform normally, all three classes may receive their contractual payments.
Now imagine the pool experiences losses.
If losses total $5 million and the junior tranche is designed to absorb the first losses, that $5 million could be absorbed entirely by the $10 million junior position, leaving the senior and mezzanine principal protected from that particular loss.
If losses rise to $15 million, the junior position could be exhausted and the next layer could begin absorbing losses.
The important lesson is not the exact percentages. It is the sequence.
The same pool of assets can produce very different investment outcomes depending on which tranche an investor owns.
What Happens When the Underlying Assets Perform Well?
Good performance does not necessarily mean every tranche receives identical benefits.
Senior investors generally receive their contractual payments according to the waterfall. Junior investors may receive the residual cash flows after higher-priority obligations have been satisfied.
The equity or residual position can therefore behave very differently from a senior note.
This is one reason structured-finance analysis focuses on the entire capital structure, rather than evaluating a security in isolation.
What Happens When Borrowers Default?
Defaults reduce the cash available from the underlying assets.
Suppose a pool contains hundreds or thousands of loans. Some borrowers may miss payments or default. The resulting losses are allocated according to the transaction’s contractual rules.
A typical senior-subordinated structure might expose the junior tranche first, followed by mezzanine positions, with senior investors affected only after available credit protection is exhausted.
The Federal Reserve has described this mechanism as a hierarchy in which the most subordinate position can absorb losses before more senior investor positions.
This is the core economic purpose of subordination.
Where Are Tranches Used in Finance?
Tranches are most strongly associated with securitization and structured finance, but the word can also appear in other financing arrangements.
Mortgage-Backed Securities (MBS)
Mortgage-backed securities represent claims on cash flows from pools of mortgage loans. More complicated mortgage structures can divide those cash flows into multiple classes, or tranches, with different priorities, maturities, coupon characteristics, and prepayment exposures.
This matters because mortgage borrowers do not always repay according to the original schedule. Refinancing, property sales, and changes in interest rates can alter the timing of cash flows.
Therefore, two tranches backed by the same mortgages can have different prepayment and maturity characteristics.
Asset-Backed Securities (ABS)
ABS can be backed by pools of assets such as:
- Auto loans
- Consumer loans
- Student loans
- Credit-card receivables
- Other financial receivables
The securities can then be divided into different classes with varying risk and payment characteristics. SEC-filed materials describe ABS risks as depending not only on the underlying collateral but also on factors such as the originator, servicer, structure, interest rates, and availability of information.
Collateralized Loan Obligations (CLOs)
A CLO generally involves a portfolio of corporate loans whose cash flows support multiple securities or interests with different priorities.
CLO structures can include senior notes, mezzanine positions, and an equity or residual interest. The senior classes generally have priority over the lower-ranking classes.
CLO analysis can become sophisticated because investors must consider not just individual loan quality but also diversification, default assumptions, reinvestment rules, coverage tests, and the structure’s waterfall.
Collateralized Debt Obligations (CDOs)
CDOs historically became one of the most widely discussed examples of structured products using tranching.
The basic idea is similar: underlying credit exposures support securities with different seniority levels.
The financial crisis demonstrated why understanding the structure matters. A tranche’s label or rating cannot be separated from the quality of the collateral, assumptions used in modeling, and protections built into the transaction.
Commercial Mortgage-Backed Securities (CMBS)
CMBS are backed by commercial real estate loans.
Different classes can have different levels of payment priority and exposure to credit and property-market risks. The Federal Reserve has described CMBS structures in which mortgage cash flows move through a waterfall from more senior to more subordinate investors.
Tranche vs. Other Financial Terms
The word “tranche” is sometimes confused with other financial terms because it describes a structural concept rather than one specific type of security.
| Term | Meaning | How it differs from a tranche |
| Tranche | A portion/class within a larger structure | The structural division itself |
| Security | A financial instrument representing an investment claim | A tranche may be represented by a security |
| Loan | Money advanced to a borrower | A loan facility can contain separate tranches |
| Installment | A scheduled payment | A tranche can be a funding portion, not merely a payment |
| Class | A category or series of securities | Often used similarly to tranche in structured finance |
| Securitization | Process of packaging financial assets and issuing securities | Tranching is one structural feature of securitization |
Tranche vs. Security
A tranche is not necessarily synonymous with security.
In many securitizations, each tranche corresponds to a particular class of securities. But the more useful mental model is:
The transaction is the whole structure; the tranches are its separate layers.
Tranche vs. Installment
This distinction becomes especially important outside structured finance.
If a company receives $30 million in financing today and another $20 million after reaching a contractual milestone, the second amount may be called a tranche of funding.
That does not necessarily involve senior and junior credit-risk layers.
What Is a Tranche in a Loan or Investment?
In lending and investment agreements, tranche can simply mean a distinct portion of financing.
For example, a financing commitment could be divided into:
- An initial funding tranche
- A second tranche released after a milestone
- A later tranche subject to additional conditions
The terms may vary according to the transaction.
Tranches in Business and Project Financing
A lender or investor may release funding in stages rather than providing the entire commitment immediately.
This can help align financing with a project’s progress. It can also give the financier an opportunity to reassess conditions before releasing additional capital.
The drawback is that the borrower may face funding uncertainty if the conditions for later tranches are difficult to meet.
Tranches in Venture Capital and Private Equity
A startup financing agreement may describe capital as being provided in multiple tranches.
For example, investors could commit a total amount but release portions after agreed milestones.
Here, “tranche” is primarily about timing and conditions of funding, not necessarily the seniority hierarchy found in securitization.
That distinction is crucial.
Not every use of “tranche” involves senior, mezzanine, and junior securities. Context determines the meaning.
How Tranche Risk Is Measured
A tranche should be evaluated at two levels:
- What risk exists in the underlying assets?
- How does the structure distribute that risk?
Looking at only one is insufficient.
Credit Risk
Credit risk comes from borrowers or counterparties failing to meet their obligations.
Important questions include:
- How likely are defaults?
- How severe could losses be?
- Are assets diversified?
- Are certain borrowers, industries, or regions heavily concentrated?
- How much collateral supports the underlying obligations?
Structural Risk
Even a strong asset pool can produce complicated outcomes if the structure is difficult to understand.
Review:
- Seniority
- Subordination
- Payment waterfalls
- Triggers
- Coverage tests
- Reserve accounts
- Credit enhancement
- Principal allocation rules
Interest-Rate Risk
Interest-rate changes can affect the market value and cash-flow characteristics of structured securities.
The effect depends on the instrument. Mortgage-related tranches can be particularly sensitive because interest rates influence borrower refinancing and prepayment behavior. Investor.gov specifically identifies prepayment and market risks as important considerations for mortgage-backed securities and CMOs.
Prepayment and Extension Risk
Prepayment risk occurs when borrowers repay earlier than expected.
Extension risk is the opposite problem: payments may arrive later than expected.
Both can affect the timing and value of tranche cash flows.
Liquidity Risk
A security can be theoretically valuable yet difficult to sell quickly at an attractive price.
This matters particularly for complex or thinly traded structured products.
SEC-filed disclosures commonly identify liquidity, valuation, credit, interest-rate, prepayment, and extension risks for asset-backed securities.
How Credit Ratings Apply to Tranches
Different tranches backed by the same pool can receive different credit ratings.
Why?
Because the rating is influenced not only by the quality of the underlying assets but also by where a tranche sits within the structure and how much protection stands beneath it.
A senior tranche may benefit from substantial subordination below it. A junior tranche has little or no such protection.
Why Can a Senior Tranche Have a High Rating?
Suppose a pool contains assets with varying levels of credit risk.
If the structure places a substantial amount of junior capital beneath a senior tranche, that junior capital may absorb losses before the senior tranche is affected.
This is one form of credit enhancement.
The SEC has described subordination as a mechanism in which lower-priority classes provide credit support to higher-priority classes.
Can a Tranche Be Safer Than the Average Asset in the Pool?
Yes, in the sense that structural protections can reduce the senior tranche’s exposure to initial losses in the underlying pool.
That does not mean the tranche is immune to losses.
The distinction is important:
Underlying-asset risk ≠ tranche risk.
The tranche is exposed to the underlying assets through a particular structural position.
What a Credit Rating Does Not Tell You
A rating is useful information, but it is not a guarantee.
A careful reader should also examine:
- Collateral composition
- Historical performance
- Structural protections
- Assumptions
- Stress scenarios
- Waterfall mechanics
- Liquidity
- Legal terms
How to Read a Tranche in a Financial Deal
If you encounter a tranche in an offering document, loan agreement, or structured-finance report, avoid jumping directly to its coupon or rating.
Use this sequence instead.
1. Identify the Underlying Assets
Ask what actually generates the cash.
Are they mortgages, corporate loans, auto loans, consumer receivables, or something else?
2. Find the Tranche’s Position
Determine whether it is:
- Senior
- Mezzanine
- Subordinated
- Equity/residual
- Or another specifically defined class
Do not rely solely on the name.
3. Read the Waterfall
Find out exactly how interest and principal are distributed.
A simple diagram can sometimes reveal more than a page of marketing language.
4. Determine Who Absorbs Losses First
Look for subordination and credit-enhancement provisions.
Ask how much protection exists below the tranche.
5. Check the Triggers
Some structures can change how cash is distributed when performance deteriorates.
A transaction might redirect cash toward senior obligations when specified tests are breached.
6. Examine Cash-Flow Risks
Check:
- Expected maturity
- Prepayment assumptions
- Interest-rate exposure
- Extension risk
- Reinvestment assumptions
- Liquidity
7. Compare Yield With Risk
Only after understanding the structure should you ask whether the return appears adequate for the risks being taken.
Common Mistakes People Make About Tranches
Mistake 1: Thinking Senior Means Risk-Free
Senior means higher priority, not guaranteed safety.
Severe deterioration in the underlying assets can eventually affect senior positions if available credit protection is exhausted.
Mistake 2: Choosing the Highest Yield Automatically
A higher yield may compensate investors for greater exposure to defaults, losses, liquidity problems, or complex cash-flow behavior.
Mistake 3: Assuming All Tranches Have Different Underlying Assets
Often, several tranches are backed by the same pool of assets.
What changes is the contractual claim on the resulting cash flows.
Mistake 4: Treating Every Tranche the Same Way
A mortgage tranche, CLO tranche, and staged project-finance tranche can have very different economics.
Mistake 5: Looking Only at the Rating
A rating does not replace structural analysis.
The underlying collateral, waterfall, triggers, and transaction documents still matter.
Mistake 6: Confusing a Funding Tranche With a Risk Tranche
In a business financing agreement, a tranche may simply represent a portion of committed capital released at a particular time.
That is different from a securitization tranche created to allocate credit risk.
Why Tranches Matter in Modern Finance
The real value of tranching is not complexity for its own sake. It is the ability to allocate financial risk and cash-flow rights more precisely.
A pension fund, bank, insurance company, specialist investor, or other market participant may have different requirements. One investor may prioritize payment protection; another may seek greater income and accept greater loss exposure.
Tranching can make it possible for these investors to participate in different parts of the same broader transaction.
But flexibility comes with a cost.
The more elaborate the structure becomes, the more important it is to understand:
- What generates the cash?
- Who gets paid first?
- Who takes losses first?
- What happens when performance deteriorates?
- What contractual triggers can change the waterfall?
- How easy is the security to value or sell?
That is why experienced analysts look beyond labels such as senior, AAA, or high yield.
They study the mechanics underneath.
A Practical Tranche Analysis Checklist
Before evaluating any tranche, work through this checklist:
| Question | Why it matters |
| What backs the transaction? | Determines the source of cash flows and underlying credit risk |
| What exactly does the tranche own or represent? | Clarifies the investor’s legal/economic claim |
| Where is it in the payment hierarchy? | Determines payment priority |
| Who absorbs losses first? | Shows how downside is allocated |
| What credit enhancement exists? | Indicates the protection available to senior claims |
| What are the triggers? | Shows when normal cash-flow rules can change |
| What are the maturity and prepayment assumptions? | Helps assess timing risk |
| What is the expected yield? | Measures potential compensation |
| How liquid is the position? | Matters if the investor needs to sell |
| What do the transaction documents say? | The documents, not the marketing label, govern the rights |
A particularly useful habit is to draw the waterfall yourself.
If you cannot explain where one dollar of incoming cash goes, you probably do not yet understand the tranche.
Conclusion:
A tranche in finance is best understood as a distinct layer within a larger financial arrangement. Its importance comes from what that layer is entitled to receive—and what risks it must absorb. Seniority, subordination, waterfalls, credit enhancement, and the quality of the underlying assets all work together to determine the economics of a tranche. The word can also describe staged funding, so context matters. One final actionable tip: whenever you encounter a tranche, ignore the label for a moment and trace the money—identify the underlying assets, payment order, loss allocation, and conditions that can change the waterfall. A common mistake to avoid is treating a high rating or attractive yield as the whole story. The strongest understanding comes from seeing the structure behind the number. In finance, the position of the slice can matter as much as the size of the pie.
FAQs
Q1. What is a tranche in finance in simple terms?
A tranche is a portion of a larger financial transaction that has specific rights to cash flows, repayment, or risk. In structured finance, multiple tranches can be backed by the same assets but have different payment priorities, risk levels, maturities, and expected returns.
Q2. What is an example of a tranche?
Imagine $100 million of loans supporting several classes of securities. The first $70 million could form a senior tranche, $20 million a mezzanine tranche, and $10 million a junior tranche. The classes could have different payment priorities and loss exposure even though they rely on the same underlying loan pool.
Q3. What are the main types of tranches?
A common structured-finance hierarchy includes senior, mezzanine, and junior or equity tranches. However, real transactions can contain several classes with more complicated priorities. Some structures also have multiple senior tranches that differ in timing or other characteristics.
Q4. Why are senior tranches considered less risky?
Senior tranches generally receive higher payment priority and may have subordinated capital beneath them that absorbs losses first. That structural protection can reduce credit-loss exposure, although senior status does not make a tranche risk-free.
Q5. Is a tranche the same as a bond?
Not necessarily. A bond is a type of financial security, while a tranche describes a portion or class within a larger structure. A tranche may be represented by bonds or notes, but the terms are not interchangeable in every financial transaction.